
Pacifecon research manager Philip Dawes takes a look at the latest Market Watch reports that focus on private, central government, and council sectors.
Pacifecon’s latest two Market Watch reports are part of a trio looking at New Zealand’s private, central government and council sectors. Each month sheds some interesting light on where the dollars are being spent, and on what kind of projects.
In addition to the featured sectors, the report also provides general information on projects around the country and how the market is trending, letting you know what activity is happening and when.
I lead the 30-strong local research and edit team, and we’ve been looking at projects around the country. A 6% increase saw 2153 new projects in May and 1985 new projects in June — and it will be interesting to see if this trend continues for July. Auckland has 45% of the country’s private sector pipeline and 30% of the value, while it also holds 30% of the central government sector and 53% of the value.
At the end of May 2026, Pacifecon had 10,398 private sector pipeline projects listed at a value of $227 billion, and 1682 central government projects at a value of $112 billion in June. An example of some of the projects we’re reporting on that are in the planning stages include:
• Otago ($8.5 billion), featuring the Lake Onslow/Lake Roxburgh hydro storage scheme,
• Waikato ($5 billion), including an offshore wind farm north of Raglan, and
• Auckland ($1.3 billion), including a sustainable mixed-use neighbourhood encouraging car-less living.
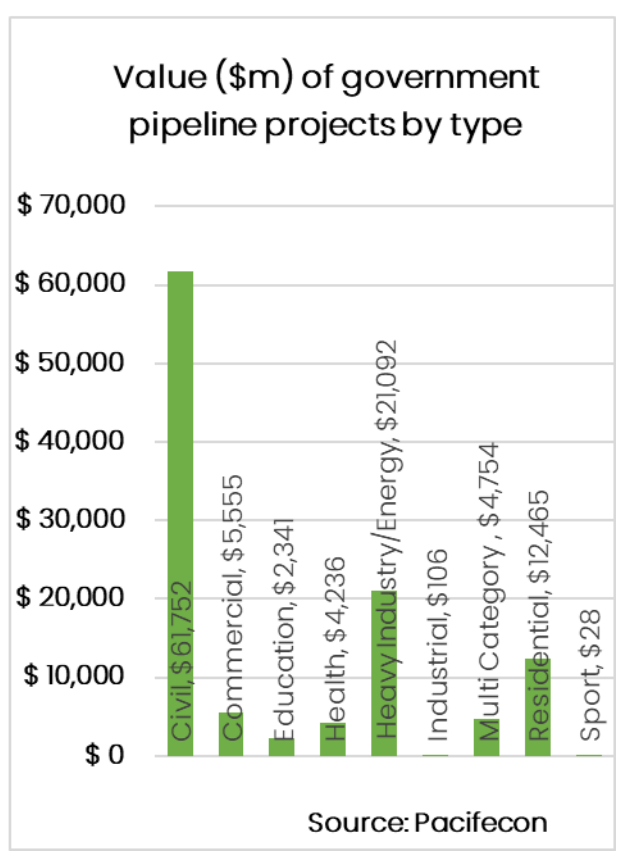
The team has favourite projects that they follow. There are always questions surrounding projects, such as who will be working on them and how, costings, what they’re going to look like, timelines, and so on. The research team answers these questions and reveals what activity is happening and when.
How the market is trending is really important to us too. Market Watch highlights the increases in the latest building consent numbers from Statistics New Zealand. In the year ended April 2026, the actual number of new dwellings consented was 39,087, up 16% from the previous 12 months.
In April this year there were 3692 new dwellings consented. The non-residential building types with the highest values were office, administration and public transport buildings at $1.6 billion, education buildings at $1.3 billion, and storage buildings at $1.2 billion.
In addition to a breakdown by project sector, each Market Watch includes commentary and graphs for the regions. It provides a comprehensive picture of planned construction across the country to help businesses with forecasting and strategic decision-making.
It’s reassuring to see that projects starting construction remain relatively steady, and the team at Pacifecon is confident that as we move into 2027, there will be an increase in activity.
Next up will be a deep dive into the local council sector — a timely focus after our recent free Local Government Reform Report, which looked at some of recent new legislation. A few of the system improvements that have been announced focus on core services, including networks infrastructure, public transport, waste, civil defence, and community facilities.
There’ll be much to report on and discuss, so keep your eyes peeled for its release at the end of August, and a breakdown in next month’s issue of Building Today.
Mention BT for a free Market Watch report!
• Be informed, make strategic decisions based on projects planned and what has started, drive business growth, understand which regions are right for your future, and identify which sectors are growing in the regions.
Head to pacifecon.co.nz/resources/market-watch/ to download sample reports, or contact us today to order your copy of Market Watch at projects@pacifecon.nz. Mention that you saw us in Building Today to receive a complimentary Market Watch.


